Commercial Closings in Ontario: What Buyers Should Know Before Purchasing a Business

A practical guide for business owners and prospective purchasers from Ahlawat Law Professional Corporation Buying an existing business can be an efficient way to step into an operating enterprise with customers, employees, inventory, equipment, premises, intellectual property, and revenue already in place. It can also expose a buyer to problems that are not obvious at first glance, including unpaid taxes, hidden security interests, weak contracts, employee claims, regulatory issues, or a lease that cannot be assigned on acceptable terms. That is why the closing stage matters so much. A commercial closing is not simply the moment when the buyer pays the purchase price and receives the keys. It is the point at which the parties confirm exactly what is being bought, whether required approvals have been obtained, whether risks have been allocated properly, and whether the documents on which the business depends can actually be transferred or preserved. For Ontario buyers, a careful closing process is often the difference between acquiring a functioning business at the expected value and inheriting avoidable liabilities. Why the Closing Stage Matters By the time a deal reaches closing, the headline business terms may already feel settled. In practice, however, many of the most important issues are resolved only in the final stretch: searches are reviewed, closing conditions are checked, financing is finalized, security interests are discharged, assignments are signed, working capital and other adjustments are confirmed, and the purchase agreement is tested against the facts uncovered in due diligence. If this stage is rushed, the buyer may discover after closing that a key contract was terminable on short notice, a landlord consent was never secured, a licence could not be transferred, or a lender still has a registration against core assets. Those are problems that can be expensive to fix once the money has changed hands. A disciplined closing process is therefore a risk-management exercise, not administrative cleanup. Asset Purchase or Share Purchase? One of the earliest and most important decisions is whether the transaction will be structured as an asset purchase or a share purchase. In an asset purchase, the buyer acquires selected assets of the business, such as inventory, equipment, goodwill, trade names, receivables, intellectual property, leasehold interests, and contracts that can be assigned. Buyers often prefer this structure because they can identify which liabilities they are willing to assume and leave the seller’s corporation behind, subject to important exceptions and practical risks. In a share purchase, the buyer acquires the shares of the operating corporation itself. That can make continuity easier because the corporation remains the contracting party, the employer, and the permit holder, but it also means the corporation keeps its history. If the target has undisclosed tax exposure, litigation risk, employment liabilities, regulatory problems, or warranty obligations, those issues do not disappear simply because ownership changes. The asset-versus-share decision shapes the entire transaction, including due diligence, consents, tax analysis, financing, and closing documents, so it should be addressed at the outset. Start with a Clear Letter of Intent A carefully drafted letter of intent, term sheet, or conditional offer can save time and reduce misunderstandings. It should usually address the proposed purchase price, transaction structure, deposit, payment terms, vendor financing if any, working-capital adjustments, due-diligence and financing conditions, required third-party approvals, the proposed closing date, and any transition assistance expected after closing. It is also common to address confidentiality and exclusivity. Even where the commercial terms are intended to be non-binding, some provisions, such as confidentiality, access, expense allocation, exclusivity, or governing law, may be legally binding. Buyers should not treat the letter of intent as a casual placeholder. Due Diligence Before Closing Financial Records and Quality of Earnings Due diligence is the buyer’s opportunity to verify the seller’s statements and determine whether the business performs and complies as represented. On the financial side, buyers commonly review at least three years of financial statements, tax returns, notices of assessment or reassessment, GST/HST filings, payroll remittance records, bank and merchant statements, accounts receivable and payable aging, inventory reports, capital expenditure records, and current year-to-date results. The goal is not only to confirm revenue, but to understand the quality of earnings. Owner compensation, personal expenses run through the business, related-party transactions, non-recurring items, deferred maintenance, unusual accounting entries, family members on payroll, and expected post-closing cost increases can all affect value. Tax and Remittance Review Tax diligence is especially important in a share purchase because the corporation retains its tax history. Buyers should understand the status of corporate income tax, GST/HST, payroll source deductions, EI and CPP remittances, worker classification issues, audits, objections, outstanding assessments, interest, and penalties. Unremitted source deductions and GST/HST can create serious exposure. In an asset deal, buyers should also pay attention to the allocation of the purchase price among asset classes, GST/HST treatment, available tax elections, possible recapture issues, and whether land transfer tax may apply if real property is included. Contracts and Leases Contracts and leases deserve focused review because they often determine whether the business can continue operating as expected on day one. Material agreements may include customer contracts, supplier and distribution arrangements, equipment leases, financing documents, franchise agreements, software licences, service contracts, advertising agreements, intellectual property licences, and government or institutional contracts. Buyers should look closely at assignment restrictions, change-of-control clauses, automatic renewals, termination rights, minimum purchase obligations, exclusivity provisions, pricing adjustments, personal guarantees, and indemnity obligations. If the business depends on its premises, the commercial lease may be one of the most important assets. Remaining term, renewal rights, base rent and additional rent, common area charges, maintenance obligations, permitted use, relocation or demolition rights, assignment provisions, guarantees, defaults, and arrears should all be reviewed carefully. In many cases, landlord consent should be an express condition of closing. Employees, Licences, Regulatory Compliance, and Intellectual Property Employee, licensing, regulatory, and intellectual-property issues can also determine whether a transaction works in practice. Buyers should request an employee schedule showing start dates, positions, compensation, bonuses, vacation entitlement and accruals, benefits, written agreements, leave status, discipline
What Should Be Included in a Unanimous Shareholders’ Agreement in Ontario?

If two or more people own a corporation together, a Unanimous Shareholders’ Agreement—often called a USA—is one of the most important documents to put in place early. A USA sets out the rules between the shareholders. It can deal with decision-making, share transfers, dispute resolution, exits, and what happens if one shareholder dies, becomes disabled, divorces, or simply wants out. For many business owners, the real question is not whether a USA is useful. It is: what should it actually include? The short answer is that there is no one-size-fits-all checklist. However, in Ontario, there are certain features that a USA should include if it is going to properly protect the business and the people involved. What Is a Unanimous Shareholders’ Agreement? A Unanimous Shareholders’ Agreement is a written agreement among all shareholders of a corporation. In Ontario, it can do more than a regular shareholders’ agreement. It can also restrict some or all of the powers that would otherwise belong to the directors. In practical terms, that means a USA can shift certain decision-making powers from the board to the shareholders themselves. For closely held corporations, family businesses, and founder-owned companies, that can be very useful. It allows the owners to agree in advance on how important decisions will be made and how difficult situations will be handled. What Must Be Included for It to Be a True USA? At a minimum, a proper USA should: If those elements are missing, the agreement may still operate as a contract between some or all shareholders, but it may not qualify as a true unanimous shareholders’ agreement. That legal distinction matters because a valid USA can affect how the corporation is managed and who has authority to make decisions. What Should Be Included in a Well-Drafted USA? Even if the minimum legal requirements are met, a basic agreement may still leave major gaps. A strong USA should usually address the following areas. 1. The Parties and the Corporation The agreement should clearly identify: This sounds simple, but accuracy matters. If ownership is not described properly, disputes can arise later over voting rights, control, and entitlements. 2. How the Business Will Be Managed A USA should explain how decisions will be made. This section often deals with: This is especially important where the shareholders want to keep direct control over major business decisions rather than leaving them entirely to the board. 3. Important Decisions That Need Special Approval Not every decision should be made by a simple majority. A good USA should list the major decisions that require: These decisions often include: This type of clause helps protect minority shareholders and reduces the risk of one group making major changes without broad agreement. 4. Rules About Selling or Transferring Shares One of the most important parts of any USA is the section on share transfers. Without clear restrictions, a shareholder may try to sell shares to an outside party, transfer shares to a spouse or family member, or otherwise change the ownership structure in a way the other owners never intended. A USA should usually address: For private corporations, transfer restrictions are often essential. 5. What Happens if a Shareholder Wants to Leave A good USA should plan for exits before there is tension. This part of the agreement may deal with: Some agreements include a shotgun clause or other buy-sell mechanism. Others set out a step-by-step process for offering shares to the remaining owners first. The right structure depends on the size of the business, the bargaining power of the shareholders, and whether all owners are active in the company. 6. How the Shares Will Be Valued A buyout clause is only useful if the agreement also explains how the shares will be priced. A USA should clearly say whether value will be determined by: Unclear valuation clauses are a common source of shareholder disputes. The more precise the agreement, the better. 7. Death, Disability, Incapacity, or Bankruptcy A USA should address what happens if a shareholder: This is one of the most important practical sections in the agreement. Without a clear plan, the remaining shareholders may find themselves in business with an estate trustee, a family member, or another unexpected party. A properly drafted USA can set out whether the shares must be sold, who can buy them, and how payment will be made. 8. Divorce and Family Law Issues In owner-managed and family-run corporations, marital breakdown can create serious business complications. A USA often includes provisions intended to reduce that risk, such as: This does not eliminate all family law issues, but it can help protect the corporation from unwanted disruption. 9. Future Funding and Capital Contributions Businesses often need more money over time. A USA should deal with what happens if the corporation needs additional funding. This section may address: This is particularly important in newer or growing businesses. 10. Confidentiality and Restrictive Covenants Where shareholders are actively involved in the business, the agreement may also include: These clauses are designed to protect the business if a shareholder leaves and later competes or attempts to take customers, staff, or confidential information. They must be drafted carefully. Restrictions that are too broad may be difficult to enforce. 11. Dispute Resolution and Deadlock Disagreements between shareholders are common. A USA should provide a path for resolving them. This may include: This is especially important where ownership is split 50/50. Without a clear process, the corporation can become paralysed when the shareholders disagree. 12. How New Shareholders Become Bound If a new shareholder joins later, that person should not be able to avoid the existing agreement. A USA should include a clause requiring any new shareholder to sign an agreement to be bound by it before receiving shares. This helps preserve consistency as the corporation grows or ownership changes. 13. What Happens if Someone Breaches the Agreement A USA should also say what happens if a shareholder breaks the rules. Possible consequences may include: This section gives the agreement practical force. Common Mistakes in Shareholders’ Agreements Some

A simple guide to International contracts for Canadian startups

Starting a business in Canada is tough. Landing your first international client feels like a huge win. But that excitement can vanish fast if the contract you sign creates more problems than it solves. Let’s start with a real-world story about a client of ours. It’s a perfect example of what can go wrong. The Three-Country ‘Mix-Up‘ of a StartUp An Ontario tech startup, let’s call them “TechCo,” was thrilled to sign a deal with a big German client. Here was the setup: To keep things “simple,” the contract said the German client should pay the Indian company directly. But the contract was missing some very important details. It didn’t say which country’s courts would handle disputes, and it was silent on taxes. When a disagreement popped up, TechCo was in a world of trouble: This story shows why getting the contract right is so important. Here’s what you need to watch out for. 1. Decide Who Has “Home Field Advantage” (Jurisdiction) Every cross-border contract needs two crucial clauses right at the start: Governing Law and Jurisdiction. Why it matters: If you don’t set these rules in the contract, you could spend a fortune just figuring out where to even start a legal fight. 2. Protect Your Big Ideas (Intellectual Property) For most startups, your ideas and inventions are your most valuable assets. Your contract must protect them. Why it matters: Without clear IP protection, a foreign partner or competitor could legally copy your idea and sell it in their market, and you wouldn’t be able to do a thing about it. 3. Be Careful with People’s Information (Data Privacy) If you handle any personal information from customers or clients, you have to follow privacy laws. This gets tricky with international deals. Why it matters: A data breach on an international project can get you in trouble with the law in more than one country, costing you a lot of money and ruining your reputation. 4. Have a Plan for Disagreements (Dispute Resolution) Even with a great contract, you might still have disagreements. Instead of going straight to a long and expensive court battle, plan for a better way. Why it matters: A simple dispute resolution plan can save your business relationship and prevent a disagreement from turning into a costly legal war. 5. Get the Money Details Right (Payments and Taxes) Fuzzy details about money can sink your company. This area is full of traps, especially when dealing with the Canada Revenue Agency (CRA). Here’s how to protect yourself: The Bottom Line Doing business internationally is a fantastic way for a Canadian startup to grow. But it comes with risks. A clear, simple, and smart contract is your best line of defense. Before you sign any international deal, it’s wise to get advice from a legal expert who understands these challenges. At Ahlawat Law PC, we help Canadian startups like yours navigate the world of cross-border business safely. Don’t risk your hard work. Let’s talk before you sign.

Starting a Business in Ontario? A detailed guide to legal structures

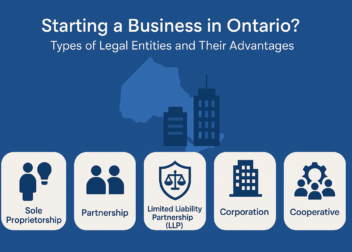
Starting a business in Ontario is an exciting step, but choosing the right legal structure is crucial. Each structure has unique legal, tax, and operational implications. This guide outlines the six main types of business structures in Ontario, their benefits, and considerations. 1. Sole Proprietorship A sole proprietorship is the simplest and most common type of business structure. It is owned and operated by one individual. Benefits: Considerations: Best For: Freelancers, tradespeople, or solo entrepreneurs starting small businesses. 2. Partnership A partnership involves two or more people sharing ownership and responsibilities for the business. Types of Partnerships: Benefits: Considerations: Best For: Family businesses, professional firms, or joint ventures. 3. Corporation A corporation is a separate legal entity from its owners (shareholders). You can incorporate provincially in Ontario or federally if you plan to operate across Canada. Benefits: Considerations: Best For: Growth-oriented businesses or those seeking investment opportunities. 4. Professional Corporation A professional corporation (PC) is a specialized type of corporation for licensed professionals such as doctors, lawyers, accountants, and architects. Benefits: Considerations: Best For: Licensed professionals looking to incorporate their practice while maintaining compliance with regulatory bodies. 5. Cooperative A cooperative is an organization owned and democratically controlled by its members, who share profits equally. Benefits: Considerations: Best For: Community-based or purpose-driven businesses focused on shared goals. 6. Joint Venture A joint venture is a temporary partnership between two or more parties working together on a specific project or goal. Benefits: Considerations: Best For: Businesses collaborating on short-term projects or initiatives. Key Considerations When Choosing a Business Structure Why Legal Advice Matters Choosing the right structure depends on your business goals, liability tolerance, tax considerations, and long-term plans. At Ahlawat Law PC, we assist entrepreneurs with: Disclaimer Important Notice: This article is intended for informational purposes only and should not be considered legal advice. Reading this article does not establish a lawyer-client relationship between you and Ahlawat Law PC. The information provided is general in nature and may not apply to your specific circumstances. For personalized advice tailored to your business needs, we recommend consulting directly with a qualified lawyer. Ahlawat Law PC is available to assist you with your legal questions and provide guidance on choosing the right business structure for your venture. Contact Us If you have questions or need further assistance, please do not hesitate to contact us at Ahlawat Law PC. We are here to help you navigate the complexities of business law in Ontario. Official Resources For more information on registering your business in Ontario: Start a Co-operative – Ontario.ca Register a Sole Proprietorship – Ontario.ca Ontario Business Registry – Start a Partnership Limited Liability Partnerships – Ontario.ca Ontario Incorporation – ServiceOntario Corporations Canada – Federal Incorporation

The Legal Foundations Every Startup Must Prioritize

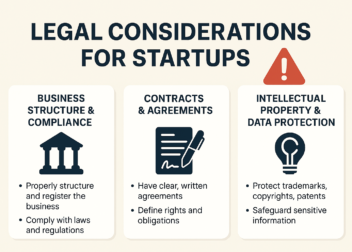
Entrepreneurs often focus on innovation, market strategy, and securing investment when launching a startup. However, overlooking legal structuring can create significant vulnerabilities, which may only become apparent during disputes, due diligence, or intellectual property violations. At Ahlawat Law PC, we understand that legal considerations may seem like an additional expense, but they function as a critical safeguard—similar to insurance. Without proper legal structuring and documentation, startups expose themselves to risks that can threaten their long-term viability. Below, we outline three fundamental legal areas that every startup should prioritize. 1. Business Structure and Regulatory Compliance Selecting the appropriate business structure is essential, as it affects liability, taxation, and access to funding. Entrepreneurs must carefully evaluate whether a sole proprietorship, partnership, or corporation best aligns with their business goals. 📌 Key Considerations: 2. Contracts and Legal Agreements Clear, well-drafted contracts serve as the foundation of any business relationship. Many startups rely on verbal agreements, which can lead to misunderstandings, disputes, or financial loss. Legal documentation is essential to define expectations, allocate risk, and provide remedies in case of non-compliance. 📌 Essential Agreements for Startups: 3. Intellectual Property Protection and Data Privacy Compliance A startup’s intellectual property and data assets are often its most valuable resources. Without adequate legal protections, businesses risk losing control over their brand, innovations, and proprietary technology. 📌 Best Practices for IP and Data Protection: Legal Costs: A Strategic Investment, Not an Expense Startups frequently view legal fees as a cost center rather than a business safeguard. However, failing to address legal risks early can result in costly litigation, lost investment opportunities, and regulatory penalties. Investing in legal protections from the outset ensures operational stability and long-term success. Conclusion A startup’s legal foundation is just as critical as its business model. Entrepreneurs who take a proactive approach to structuring, contracts, and intellectual property protection will be better positioned to scale their businesses while mitigating risks. At Ahlawat Law PC, we assist startups in navigating legal complexities with tailored legal strategies. For guidance on structuring your business or drafting essential agreements, please contact us today. Disclaimer: This article is for informational purposes only and does not constitute legal advice. For personalized legal counsel, consult a qualified lawyer. #OntarioLaw #StartupLegalProtection #BusinessLaw #CorporateLaw #IntellectualProperty #PrivacyLaw #LegalCompliance

Understanding ‘Meaningful Consent’ under PIPEDA

In Canada, organizations that collect, use, or disclose personal information must comply with the Personal Information Protection and Electronic Documents Act (PIPEDA). A key requirement under PIPEDA is obtaining meaningful consent from individuals. But what does that really mean? Simply put, it means that individuals must fully understand what they are agreeing to when they provide their personal information. What Is Meaningful Consent? Meaningful consent ensures that individuals have enough information to make an informed decision about sharing their data. It goes beyond simply obtaining a yes or no response. To be valid, consent must be clear, specific, and informed. Organizations cannot bury critical details in lengthy terms and conditions or use vague language. The Office of the Privacy Commissioner of Canada (OPC) outlines key elements for obtaining meaningful consent: Express vs. Implied Consent PIPEDA recognizes two types of consent: express and implied. Express consent means the individual clearly agrees, often by checking a box or signing a document. Implied consent may be assumed in certain situations, such as when a customer provides their address to complete an online purchase. However, for sensitive information, express consent is typically required. The Importance of Meaningful Consent Failing to obtain proper consent can lead to regulatory scrutiny, complaints, and reputational damage. With growing concerns about privacy, businesses must take consent seriously and ensure their policies align with PIPEDA’s guidelines. Best Practices for Compliance By prioritizing meaningful consent, businesses not only stay compliant but also build trust with customers. In today’s digital world, transparency and respect for privacy are key to maintaining strong relationships with consumers.

Essential Insights for establishing a Franchise in Ontario

Franchising can be an appealing route for entrepreneurs looking to start a business with an established brand. However, navigating the legal landscape of franchising can be complex. In Ontario, the Arthur Wishart Act (Franchise Disclosure), 2000 is a critical piece of legislation designed to protect franchisees and ensure fair dealing within the franchise system. Let’s break down the key aspects of this Act and highlight what prospective and current franchisees need to know.  Understanding the Arthur Wishart Act The Arthur Wishart Act is designed to create a level playing field between franchisors and franchisees. It focuses on providing franchisees with adequate information and protecting their rights throughout the franchise relationship. Here are some essential elements of the Act: Key Protections for Franchisees Why Seek Legal advice? Franchise agreements can be complex and may contain clauses that are difficult to understand. A lawyer can help you: The Arthur Wishart Act plays a crucial role in regulating the franchise industry in Ontario. By understanding your rights and obligations under this Act, you can make informed decisions and protect your investment. Whether you’re considering becoming a franchisee or are already operating a franchise, seeking legal guidance from lawyers is essential. Let’s discuss your expectations and needs.